How United Public Adjusters & Appraisers Helped Increase the Carrier’s Dwelling Valuation by More Than $681,000
CASE STUDY
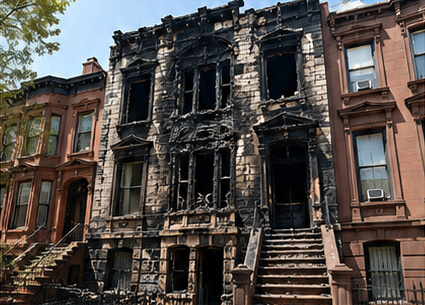
From $443,832 to More Than $1.125 Million: A Brooklyn Residential Fire-Damage Claim
Initial Carrier Valuation
$443,832.06
Final Dwelling Valuation
$1,125,039.66
Increase in RCV
$681,207.60

Percentage Increase
153.5%
Case Study Overview
A serious residential fire damaged an older architecturally distinctive home in Brooklyn. The loss involved fire, smoke, soot, and water damage, asbestos abatement, architectural services, permits, NYC building requirements, landmark-related considerations, contractor costs, and temporary housing.
Before UPA became involved, the carrier valued the dwelling claim at $443,832.06. After extensive documentation, analysis, and negotiation, the dwelling valuation increased to $1,125,039.66.
The Challenge
- Fire, smoke, soot, and water damage
- Damage to multiple building systems and finishes
- Asbestos-containing materials
- Demolition and environmental remediation requirements
- Architectural and professional services
- Permit and filing expenses
- NYC code and landmark-related requirements
- Additional living expenses during displacement
Our Public Adjuster Strategy
- Reconstructed the full scope of loss
- Challenged improper damage classification
- Documented asbestos and environmental costsAccounted for the realities of restoring an architecturally distinctive home
- Supported the family’s additional living expense claim
- Preserved the insured’s right to additional recovery
The Results
| Before (Carrier Offer) | After (UPA Outcome) | |
| Replacement Cost Value | $44,832.06 | $1,125,039.66 |
| Actual Cash Value | $412,022.73 | $1,007,804.89 |
More than 2.5x the carrier’s original valuation
Increase of $595,782.16 in Actual Cash Value
Continued pursuit of depreciation, supplements, and other covered amounts
Why This Brooklyn Fire Claim Matters
The property did not change — the depth of investigation, documentation, claim classification, and restoration analysis changed.
This claim highlights how hidden complexity, code requirements, environmental issues, professional services, and temporary housing needs can dramatically impact the true cost of restoring a home after a fire.
Frequently Asked Questions
Can a public adjuster help after the insurance company has already made an offer?
Yes. An insurance company’s initial offer does not necessarily represent the full value of a covered loss. A public adjuster can review the carrier’s estimate, inspect the damage, identify items that may have been missed or undervalued, document additional covered costs, and negotiate with the insurance company on the policyholder’s behalf.
Why can fire-damage estimates differ so significantly?
Fire claims can involve much more than the damage that is immediately visible. Smoke, soot, water used during firefighting, demolition, environmental remediation, building code requirements, specialty materials, labor costs, architectural services, and other expenses can all affect the cost of restoration.
Differences in the scope of damage, pricing, and how repairs are classified can result in significantly different estimates.
Does homeowners insurance pay for temporary housing after a fire?
Many homeowners insurance policies include Additional Living Expense coverage, often called ALE, which may help pay for reasonable additional costs when a covered loss makes the home uninhabitable.
Depending on the policy, this can include temporary housing and certain other increased living expenses, subject to coverage limits, terms, and conditions.
What is recoverable depreciation?
Recoverable depreciation is the portion of depreciation withheld from an initial Actual Cash Value payment that may be recoverable after covered repairs or replacement are completed and properly documented.
Whether depreciation is recoverable, how much can be recovered, and the requirements for receiving it depend on the terms of the insurance policy and the circumstances of the claim.

Think Your Claim May Be Undervalued?
Let our team review your claim, identify overlooked damages, and help you understand your options.
Request a Complimentary Claim Review
Every insurance claim is different. Prior results do not guarantee a similar outcome.

No Recovery. No Fee.

Or call 800-718-LOSS
Think Your Claim May Be Undervalued?
Let our team review your claim, identify overlooked damages, and help you understand your options.
Request a Complimentary Claim Review
Every insurance claim is different. Prior results do not guarantee a similar outcome.
No Recovery. No Fee.
Or call 800-718-LOSS