What happens when hurricane damage is only the beginning, and simply getting workers and building materials to the property becomes part of the cost of rebuilding?
After Hurricane Irma devastated St. John in the U.S. Virgin Islands, United Public Adjusters & Appraisers (UPA) went there as hurricane damage claims adjusters to represent property owners facing extraordinary losses. What our team encountered changed the way we understood catastrophe recovery.
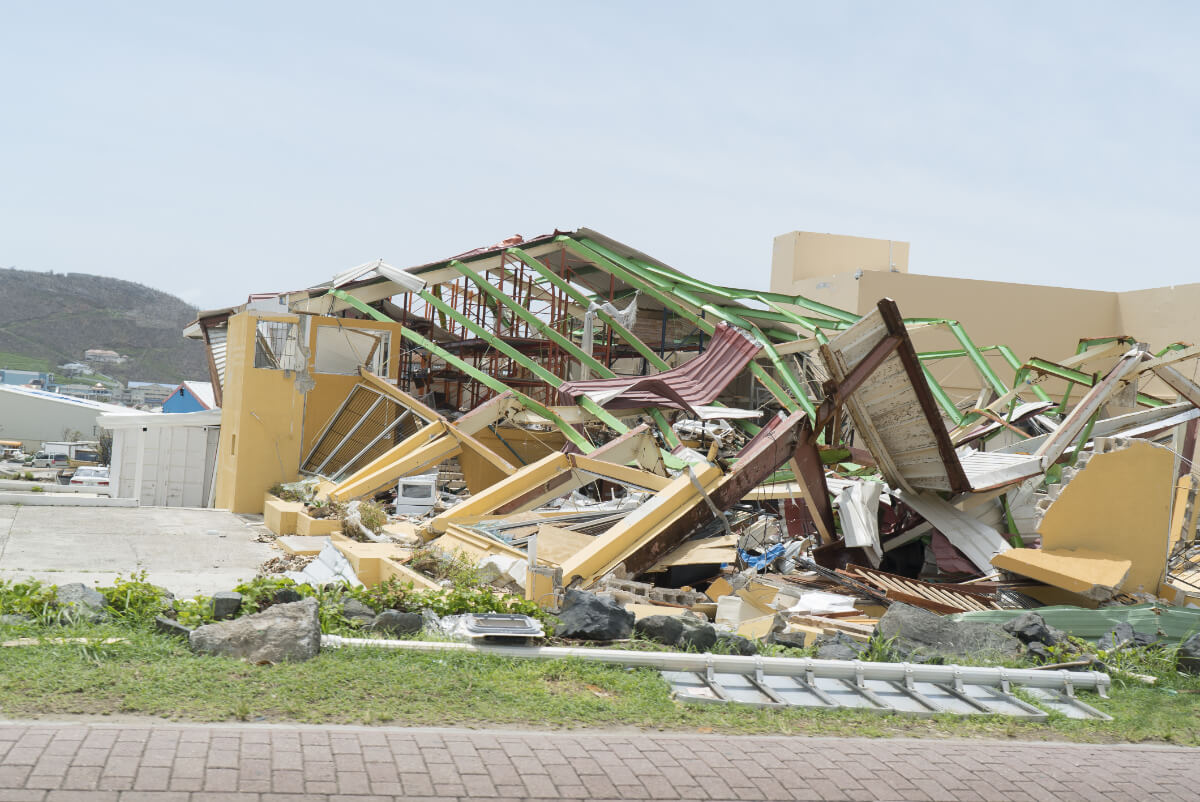
The damage was severe. Structures were compromised. Roofs were gone. Windows and exterior doors had failed. Homes and businesses were exposed to the elements. But the physical destruction was only the beginning.
The ferry affected labor and labor costs. The barge affected materials and materials costs. Geography affected productivity. Catastrophe conditions affected pricing and availability. Building codes affected reconstruction. And every one of those factors could affect the value and duration of a hurricane damage claim.
For UPA, the lesson was clear: properly documenting a catastrophic property loss means understanding what rebuilding actually requires, not simply what an estimating program says it should cost.
How UPA Helps: As a first step in assisting clients to prepare their hurricane damage claim, UPA evaluates the complete circumstances surrounding a loss, from physical damage and policy provisions to the real-world costs and logistical challenges of restoring the property.
We Went There and Saw What Recovery Really Meant
Reaching our clients’ properties was an education in itself.
Our team traveled through Puerto Rico, where hurricane damage remained visible, and continued to St. Thomas. From there came ground transportation to the ferry, the crossing to St. John, more transportation and, in some cases, difficult drives into the hills above Cruz Bay and Coral Bay.
From the air, blue tarps covered roof after roof for months after Irma.
At one residence, portions of the roof and building envelope were gone. Standing inside, we could look directly through the damaged structure at a brilliant Caribbean sky and beautiful water beyond it.
It was destruction surrounded by paradise.
But for a hurricane damage claims adjuster, the location and access challenges were not scenery. They were part of understanding what recovery would actually cost.
How UPA Helps: UPA adjusters go to the property to see the damage, assess access challenges and view surrounding conditions firsthand. That boots-on-the-ground perspective allows us to build detailed, property-specific assessments based on what is actually happening at the loss site, not simply what the damage may look like in transmitted photos viewed on a monitor in an office or on paper.
Logistics Nightmare: When the Ferry Becomes Part of the Construction Schedule
Many contractors and workers serving St. John were traveling from St. Thomas. Before reaching a Coral Bay jobsite, a worker might have to travel to the ferry terminal, cross to St. John, secure transportation and navigate difficult hillside roads.
At day’s end, the journey was reversed.
A worker’s commute alone could affect contractor productivity, mobilization, scheduling, bids and the realistic duration of reconstruction.
Obtaining building materials presented similar challenges:
Supplier → freight → St. Thomas → cargo/barge transportation → St. John → local trucking → property.
And be aware that reaching the island did not necessarily mean reaching the jobsite.
How UPA Helps: UPA examines the actual logistics behind reconstruction so that transportation, access, labor constraints and other supportable costs are considered when documenting and preparing a hurricane damage claim.
What Does That Window Really Cost?
A replacement window may have a standard price in estimating software. But after a catastrophe on St. John, the better question was:
What does it actually cost to replace this particular window, at this particular property, under these particular conditions?
The answer could involve manufacturing, mainland sourcing, freight, marine transportation, local trucking, difficult hillside access and installation.
Irma had also struck Florida, increasing regional demand for contractors, materials and suppliers. The result: these commodities were scarce, and availability may not have been immediate.
For a hurricane damage claims adjuster, understanding these conditions can be critical. A line-item estimate may not fully reflect the real-world cost of reconstruction following a widespread catastrophe.
How UPA Helps: UPA develops and supports a detailed scope of loss based on the property and actual reconstruction conditions, helping property owners present documented costs that may otherwise be overlooked or underestimated.
Additional Considerations: Building Codes Can Change What Reconstruction Requires
Older properties may face another complication: rebuilding does not necessarily mean replacing damaged components exactly as they were.
Depending on the extent of the reconstruction and applicable building requirements, compliant products or construction methods may be required, potentially including impact-rated windows and doors.
Where applicable Ordinance or Law coverage exists, the analysis may involve determining what must be reconstructed, which code requirements apply, what compliant products cost and whether increased costs fall within the policy’s coverage and limits.
Not every code upgrade is automatically covered. Coverage depends on the individual policy, applicable code, circumstances of the loss and policy limits.
How UPA Helps: UPA reviews applicable policy provisions and works to identify and document covered code-related reconstruction costs when supported by the client’s policy and circumstances.
Hotels, Restaurants, and Businesses Face a Different Kind of Loss
For St. John’s hospitality industry, physical repairs could represent only one component of a loss.
Damaged lodging inventory coincided with increased demand from contractors, engineers, adjusters, government personnel and recovery workers. Businesses could also confront utility interruptions, employee displacement, supplier problems, reduced capacity, prolonged reconstruction and, of course, loss of revenue from decreased tourism.
Depending on coverage, commercial claims may involve business income, continuing expenses, extra expense and period-of-restoration issues in addition to building damage.
How UPA Helps: UPA helps policyholders identify the full scope and documented value of covered losses while working within the terms, conditions and limits of the applicable insurance policy. We provide additional assistance as needed, including relocation and, whenever possible, help locating a temporary business site.
Being Insured Does Not Always Mean Being Adequately Insured
Irma also underscored the difference between market value and reconstruction cost.
For island and coastal properties, replacement costs may be affected by freight, labor availability, worker lodging, marine transportation, equipment, difficult site access, debris handling, code compliance and catastrophe-driven pricing.
Those realities are important to understand before disaster strikes, and especially important once a hurricane damage claim must be prepared.
How UPA Helps: UPA helps policyholders identify the full scope and documented value of their covered losses while working within the terms, conditions and limits of the applicable insurance policy. In addition to performing a thorough policy review, we can assist with the documentation and preparation of your hurricane damage claim.
After a Catastrophe, Property Owners Can Build Their Own Team
Hurricanes Harvey, Irma and Maria placed enormous pressure on the entire catastrophe-response system, changing UPA’s approach to providing hurricane damage claims assistance forever. UPA’s experience in St. John was not simply about challenging an insurance company. It was about making certain policyholders had experienced professionals on their side who understood their policy, the true extent of their damage and the complete realities of their reconstruction project.
United Public Adjusters & Appraisers has achieved nearly $1 billion in successful settlements for our clients. Our St. John experience reinforced a principle that continues to guide our work:
A property insurance loss should be evaluated according to what it actually takes to restore the property, not simply what a spreadsheet assumes the work should cost.
How UPA Helps: If your home, condominium, co-op, hotel, restaurant or commercial property has suffered hurricane damage, the UPA team, acting as your hurricane damage claim adjuster, can document the loss, review your policy, develop your hurricane damage claim and advocate for a just settlement supported by the covered damage and circumstances.
Hurricane Damage? Make Sure Your Entire Loss Is Being Considered.
The most visible destruction may be only part of your insurance claim. Reconstruction logistics, labor, transportation, code requirements, business interruption and catastrophe conditions can all affect your road to recovery.
If you need an experienced hurricane damage claims adjuster on your side, contact United Public Adjusters & Appraisers. Remember, we have realized almost one billion dollars in successful settlements for our clients. We fully understand that recovering from a catastrophic loss requires more than noting what was damaged. It requires understanding the full scope of your issue, including what it will actually take to rebuild.
Contact UPA today to discuss your property damage insurance claim. Our goal is to achieve a successful settlement for our clients, and there is no fee unless we recover for you.
Insurance coverage is subject to the terms, conditions, limitations and exclusions of the applicable insurance policy. Every claim and property presents different facts and circumstances.
MY FREE CONSULTATION
"*" indicates required fields