For Residential and Commercial Property Owners Throughout New York, New Jersey, and Connecticut, Hurricane Damage Can Lead to Costly Repairs, Unexpected Expenses, and Complicated Insurance Claims.
Hurricane Isaias is another reminder of the destructive power of severe tropical storms. High winds, torrential rainfall, falling trees, and flooding can threaten homes, businesses, and entire communities. For property owners throughout the Tri-State area, the lessons are clear: even when a hurricane makes landfall hundreds of miles away, its potential to cause widespread damage warrants serious attention.
The financial consequences can be staggering. RMS®, a leading catastrophe risk solutions company, estimated total insured losses from the 2020 Hurricane Isaias at $3 billion to $5 billion, including $400 million to $700 million in National Flood Insurance Program (NFIP) losses. Wind damage accounted for the majority of insured losses. That historic hurricane was downgraded to a tropical storm as it made landfall, yet billions in property damage occurred.
While hurricane damage claim estimates are not yet available, be aware that the October 2026 Hurricane Isaias made landfall as a Category 2 storm, with winds reaching 110 MPH as it barreled up the coast.
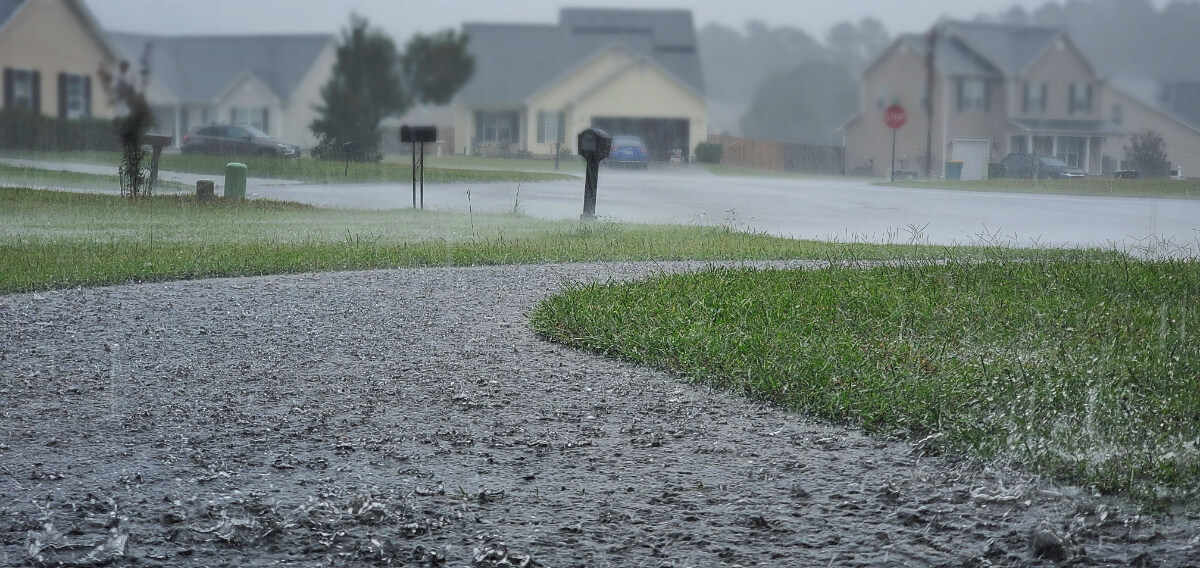
By the time Isaias reached the Tri-State area, winds had subsided somewhat; however, torrential rain forced the cancellation of most outdoor activities and events, and flooding was widespread.
For New York, New Jersey, and Connecticut property owners in the wake of Hurricane Isaias, understanding the scope of storm-related damage and preparing comprehensive hurricane damage claims are essential steps toward recovery.
Residential Hurricane Damage: What Homeowners Need to Know
Hurricane-force winds and heavy rainfall can compromise roofing systems, damage exterior structures, and allow water to penetrate homes, condominiums, townhouses, and multifamily residential properties.
Common types of residential property damage include:
- Roof damage: Missing shingles, displaced tiles, damaged flashing, and compromised roofing materials.
- Interior water damage: Saturated insulation, damaged drywall, stained ceilings, warped flooring, and affected personal belongings.
- Windows and doors: Broken glass, damaged frames, and openings compromised by windborne debris.
- Exterior damage: Fallen trees, damaged siding, fencing, garages, and other insured structures.
- Concealed damage: Moisture intrusion behind walls, beneath flooring, and within attics that may not become apparent immediately.
Importantly, a roof does not need to be completely destroyed to sustain significant damage. Even relatively minor openings can allow rainwater to enter and cause extensive deterioration.
Condominium and cooperative property claims can be especially complex because responsibility for repairs may involve association or building policies, individual unit-owner coverage, and governing documents.
How UPA Helps: United Public Adjusters & Appraisers conducts thorough on-site property assessments whenever conditions permit, documents visible and potentially concealed losses, and helps homeowners prepare detailed insurance claims that reflect the full scope of covered damage.
Commercial Hurricane Damage: When Property Losses Threaten Business Operations
For commercial property owners throughout NYC, Long Island, Westchester, New Jersey, and Connecticut, hurricane-related losses may extend far beyond structural repairs.
Office buildings, retail establishments, restaurants, warehouses, apartment buildings, and industrial facilities may experience extensive damage to roofs, equipment, inventory, and essential building systems.
Potential commercial losses include:
- Roofing and structural damage: Compromised flat roofs, roofing membranes, flashing, drainage systems, and exterior walls.
- Equipment and inventory losses: Damaged machinery, computers, merchandise, furnishings, and specialized equipment.
- Interior water damage: Affected ceilings, flooring, electrical systems, tenant improvements, and other building components.
- Business interruption: Lost revenue, continuing expenses, and additional costs resulting from covered disruptions to business operations.
When commercial property damage forces a temporary closure, relocation, or reduced operations, business income and extra expense coverage may apply, depending on policy terms and the circumstances of the loss.
How UPA Helps: UPA’s experienced public adjusters assist commercial property owners with documenting building damage, evaluating equipment and inventory losses, and preparing business interruption claims when applicable. Their detailed approach helps identify potentially overlooked losses and supports a comprehensive claim presentation.
Wind Damage vs. Flood Damage: Understanding Your Insurance Coverage
One of the most challenging aspects of hurricane damage claims is determining whether water damage resulted from wind-driven rain, storm surge, or surface flooding.
Why does this matter?
Standard homeowners insurance policies generally cover certain types of wind damage, but typically exclude flooding. Rainwater entering through a storm-damaged roof or window may qualify for coverage, depending on the policy. However, water entering a building from rising surface water generally requires separate flood insurance.
Commercial property policies may contain similar distinctions, along with specific deductibles, exclusions, and coverage limitations.
When multiple causes of damage occur during the same storm, establishing the source and extent of each loss becomes especially important.
How UPA Helps: UPA reviews policy provisions, investigates the circumstances of the damage, and helps property owners document wind-related losses and distinguish them from flood damage when preparing their insurance claims.
Five Important Steps After Hurricane Property Damage
Once conditions are safe, property owners should act promptly to protect their property and preserve essential evidence.
- Document the damage. Take photographs and videos of damaged roofs, interiors, exterior structures, equipment, inventory, and personal belongings.
- Prevent additional losses. Arrange reasonable emergency mitigation, including temporary roof protection and water extraction, when safe to do so.
- Preserve important records. Retain repair estimates, emergency service invoices, damaged-property inventories, and insurance correspondence.
- Review your insurance coverage. Understand applicable deductibles, exclusions, reporting deadlines, and potential business interruption provisions.
- Contact a licensed public adjuster. Experienced representation can help identify the full scope of covered losses and support a thoroughly documented claim.
Avoid making permanent repairs or discarding damaged materials before they have been adequately documented, except when necessary for safety or to prevent additional damage.
Hurricane Damage in NY, NJ, or CT? UPA Has Your Back!
Following a hurricane or major coastal storm, property owners may face complicated insurance provisions, extensive repair estimates, and unexpected claim disputes.
United Public Adjusters & Appraisers represents residential and commercial policyholders throughout New York, New Jersey, and Connecticut, advocating for their interests throughout the insurance claims process.
With a track record approaching $1 billion in settlements, UPA combines extensive claims experience, detailed property inspections, and determined advocacy to help policyholders pursue the settlements their insurance coverage supports.
Whether your Long Island home has sustained roof damage, your New Jersey commercial property has experienced water intrusion, or your Connecticut business faces operational disruptions, UPA is prepared to help.
Don’t Let Overlooked Damage or an Incomplete Claim Compromise Your Recovery.
A final consideration: after a major weather event, insurance carriers are inundated with property damage claims, leading to longer claims processing times and often low settlement offers. The UPA team works on your behalf with your carrier to oversee your claim’s progress and negotiate a just settlement in line with your policy limits. In short: we have your back.
Contact United Public Adjusters & Appraisers today to discuss your property damage, review your insurance claim, and learn how our team can help protect your interests.
Our goal is a successful settlement for our clients. No recovery, no fee.
MY FREE CONSULTATION
"*" indicates required fields